A benefits check can come back as a page of insurance terms that seems to say yes and no at the same time.
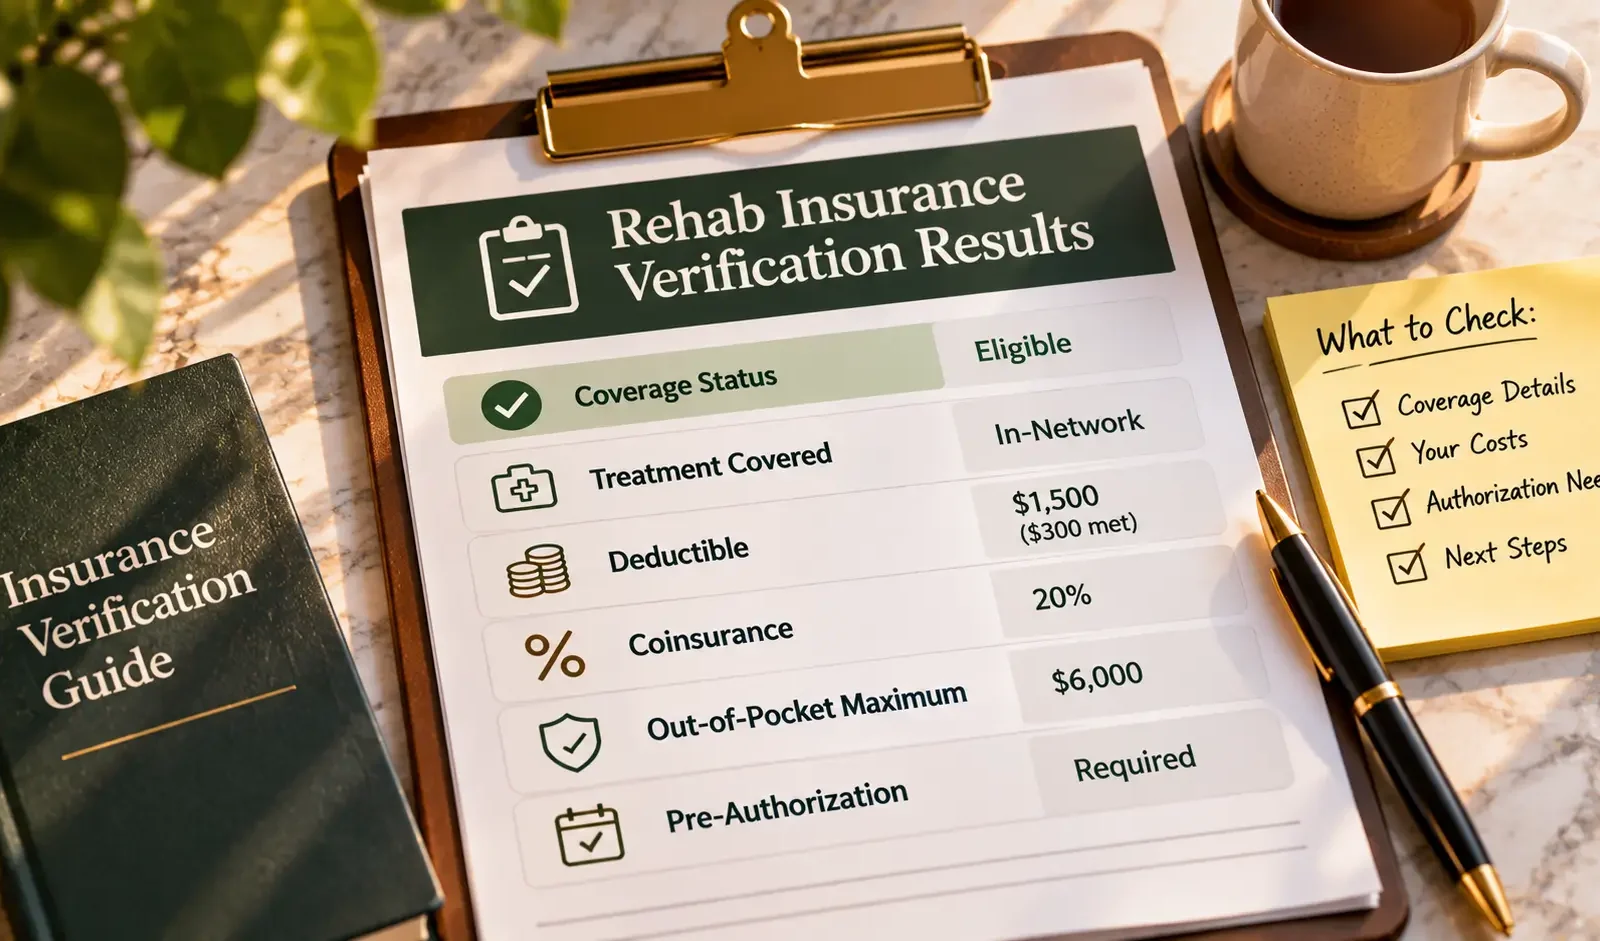
Insurance verification results show what your health plan says it may pay for rehab before you start. They usually list your network status, deductible, copay or coinsurance, out-of-pocket maximum, and whether prior authorization is needed. They are an estimate based on your plan, not a promise of payment.
Key takeaways:
- A verification is a snapshot of your benefits on the day it was run, not a guarantee of payment.
- “Covered” means the plan may pay part of the cost after your deductible and other rules apply.
- Your out-of-pocket maximum caps what you pay for covered in-network care in a plan year.
- Detox and residential care often need prior authorization, even when they are covered.
- Amenities at a luxury program are usually not part of what insurance reviews.
Haven’t checked your plan yet? Start with our luxury rehab insurance verification page, then come back here to read your results.
What is a verification of benefits for rehab?
A verification of benefits, often called a VOB, is a check of what your health plan covers for addiction or mental health treatment. The program or your insurer looks up your plan and reports the details that shape your cost.
It does not decide whether your stay will be paid. Payment for each level of care still depends on medical necessity, any required approvals, and the claims the program sends later.
How do you read your insurance verification results?
Most rehab insurance verification results include the same core items. Here is what each one means and why it matters for treatment.
| Item | What it means | Why it matters for rehab |
|---|---|---|
| Network status | Whether the program has a contract with your plan | In-network care usually costs less and counts toward your out-of-pocket maximum |
| Deductible and amount met | What you pay before the plan starts sharing costs | If you have already met much of it this year, your share may be lower |
| Copay or coinsurance | A flat fee, or a percentage of the allowed amount, usually after the deductible | A longer stay means more days of cost-sharing |
| Out-of-pocket maximum and amount met | The most you pay for covered in-network services in a plan year | It sets a ceiling on your share of covered care |
| Prior authorization | Approval the plan must give before certain care starts | Detox and residential care often need it before admission |
| Levels of care | Which services are covered, such as detox, residential, PHP, or IOP | A “yes” for outpatient care does not always mean a “yes” for residential care |
| Out-of-network benefits | Whether the plan pays anything outside its network | Many HMO plans pay nothing for planned out-of-network care |
| Plan type | Whether the plan is fully insured or self-funded | Self-funded plans follow federal rules, so some state requirements may not apply |
Ask for your plan year dates too. Deductibles and out-of-pocket totals usually reset when a new plan year starts, and that is not always January.
Our insurance coverage guide explains how self-funded and fully insured plans differ.
Does “covered” mean your insurance will pay for everything?
No. “Covered” means the plan includes that type of care as a benefit. You still pay your share, and the plan pays only for the days and services it agrees are medically necessary.
For residential treatment, the plan may approve a set number of days and then review your progress. If it decides you no longer need that level, it may approve a lower level of care instead.
A “not covered” line in your insurance verification results is worth a second look. Ask whether it applies to the service itself or only to that program, because the answer changes your options.
How can you estimate your share of the cost?
You can get a rough idea from your results in four steps:
- Note how much of your deductible is left for this plan year.
- Ask the program for its expected cost for that level of care, then apply your copay or coinsurance to the amount left after your deductible.
- Add steps 1 and 2 together, and compare the total with what is left on your out-of-pocket maximum. For covered in-network care, the maximum is usually the most you would pay this plan year.
- Add anything the plan will not pay for, such as amenities or out-of-network charges.
HealthCare.gov notes that the out-of-pocket maximum does not include your premiums, services your plan does not cover, or out-of-network care. Some plans also set a separate limit for out-of-network care, or none at all.
Treat your number as a rough guide. Ask the program for a written estimate based on your results before you commit.
What if the program is out-of-network?
Your results may show out-of-network benefits, a separate deductible, or no coverage at all outside the network. When there are benefits, the plan usually pays based on its own allowed amount, not the program’s full charge.
The program may then bill you for the difference, which is called balance billing. An in-network provider generally cannot do this for covered services.
Sometimes a plan agrees to a single case agreement, which treats one out-of-network provider like an in-network one for a specific patient. These are not guaranteed. Our guide to out-of-network rehab coverage explains how they usually work.
Why can your results change after treatment starts?
Your insurance verification results show your benefits on the day the check was run. Several things can change the picture later:
- The plan approves fewer days than expected, or reviews care sooner.
- A new plan year starts and your deductible resets.
- Your job or coverage changes during treatment.
- You move to a different level of care that needs its own approval.
Stay in touch with the program’s admissions or billing team so you hear about changes early.
What isn’t part of an insurance verification at a luxury program?
Your insurer reviews clinical care, such as detox, therapy, and medical services. Private suites, massage, personal training, and similar extras are usually outside that review, so a verification rarely tells you what they cost.
Ask the program to split its estimate into two parts: the clinical care your plan may cover, and the extras you would pay for in full. Our guide to luxury rehab cost explains what usually drives the price.
If your plan covers less than you hoped, our page on private pay luxury rehab explains other ways people pay.
What should you do after you get your results?
Once your insurance verification results are in, take these steps before you choose a program:
- Ask for your results in writing, with a reference number if your insurer gave one.
- Confirm who will request prior authorization, and when.
- Ask for a written estimate that lists clinical care and extras separately.
- Check your plan year dates and how much of your deductible is left.
- Plan how you will pay your share, including any deposit the program asks for.
Need help right now? Call our admissions team at (754) 283-6425. If anyone is in immediate danger, such as an overdose or a medical emergency, call 911.
Results in hand but still unsure? Our admissions team can go through your insurance verification results line by line and explain what they may mean for your stay. You’ll find our number at the end of this page.
Frequently asked questions
Is an insurance verification a guarantee of payment?
No. It shows what your plan’s records say on the day of the check. Final payment depends on medical necessity, any required approvals, and the claims the program submits.
What does insurance verification mean for rehab?
It means checking your plan’s benefits for addiction or mental health treatment before you start. The goal is to learn your likely costs and any approvals you need, so there are fewer surprises later.
How long does a verification of benefits take?
Timing depends on your insurer and your plan. Simple checks can be quick, while plans that use a separate behavioral health company may take longer.
Why do the program’s results differ from what my insurer told me?
The two may have checked different services, dates, or network details. Ask each side which level of care and which provider they looked up, then compare.
Do I need a new verification if my level of care changes?
Your benefits usually stay the same, but the new level of care often needs its own approval. Our guide to UMR prior authorization for rehab shows how this works on one common type of employer plan.
Table of Contents
Got your results and not sure what they mean?
A page of insurance terms is hard to read when you are already worried about getting help. Our admissions team can review your insurance verification results with you, explain what your plan may cover, and walk you through how our program works.
Call (754) 283-6425 to go over your results, or verify your insurance online if you haven’t checked your plan yet.
If your benefits look limited, we will tell you plainly, so you can weigh your options before you decide.

3 Comments